As Aaron Paker, partner at Life Point Law, will tell you, few questions cause more concern and confusion than Medicaid’s so-called Five-Year Lookback. The complexities surrounding this critical rule are a big part of the reason why no one should try navigating Medicaid’s regulations without the services of a highly-qualified and experienced guide.
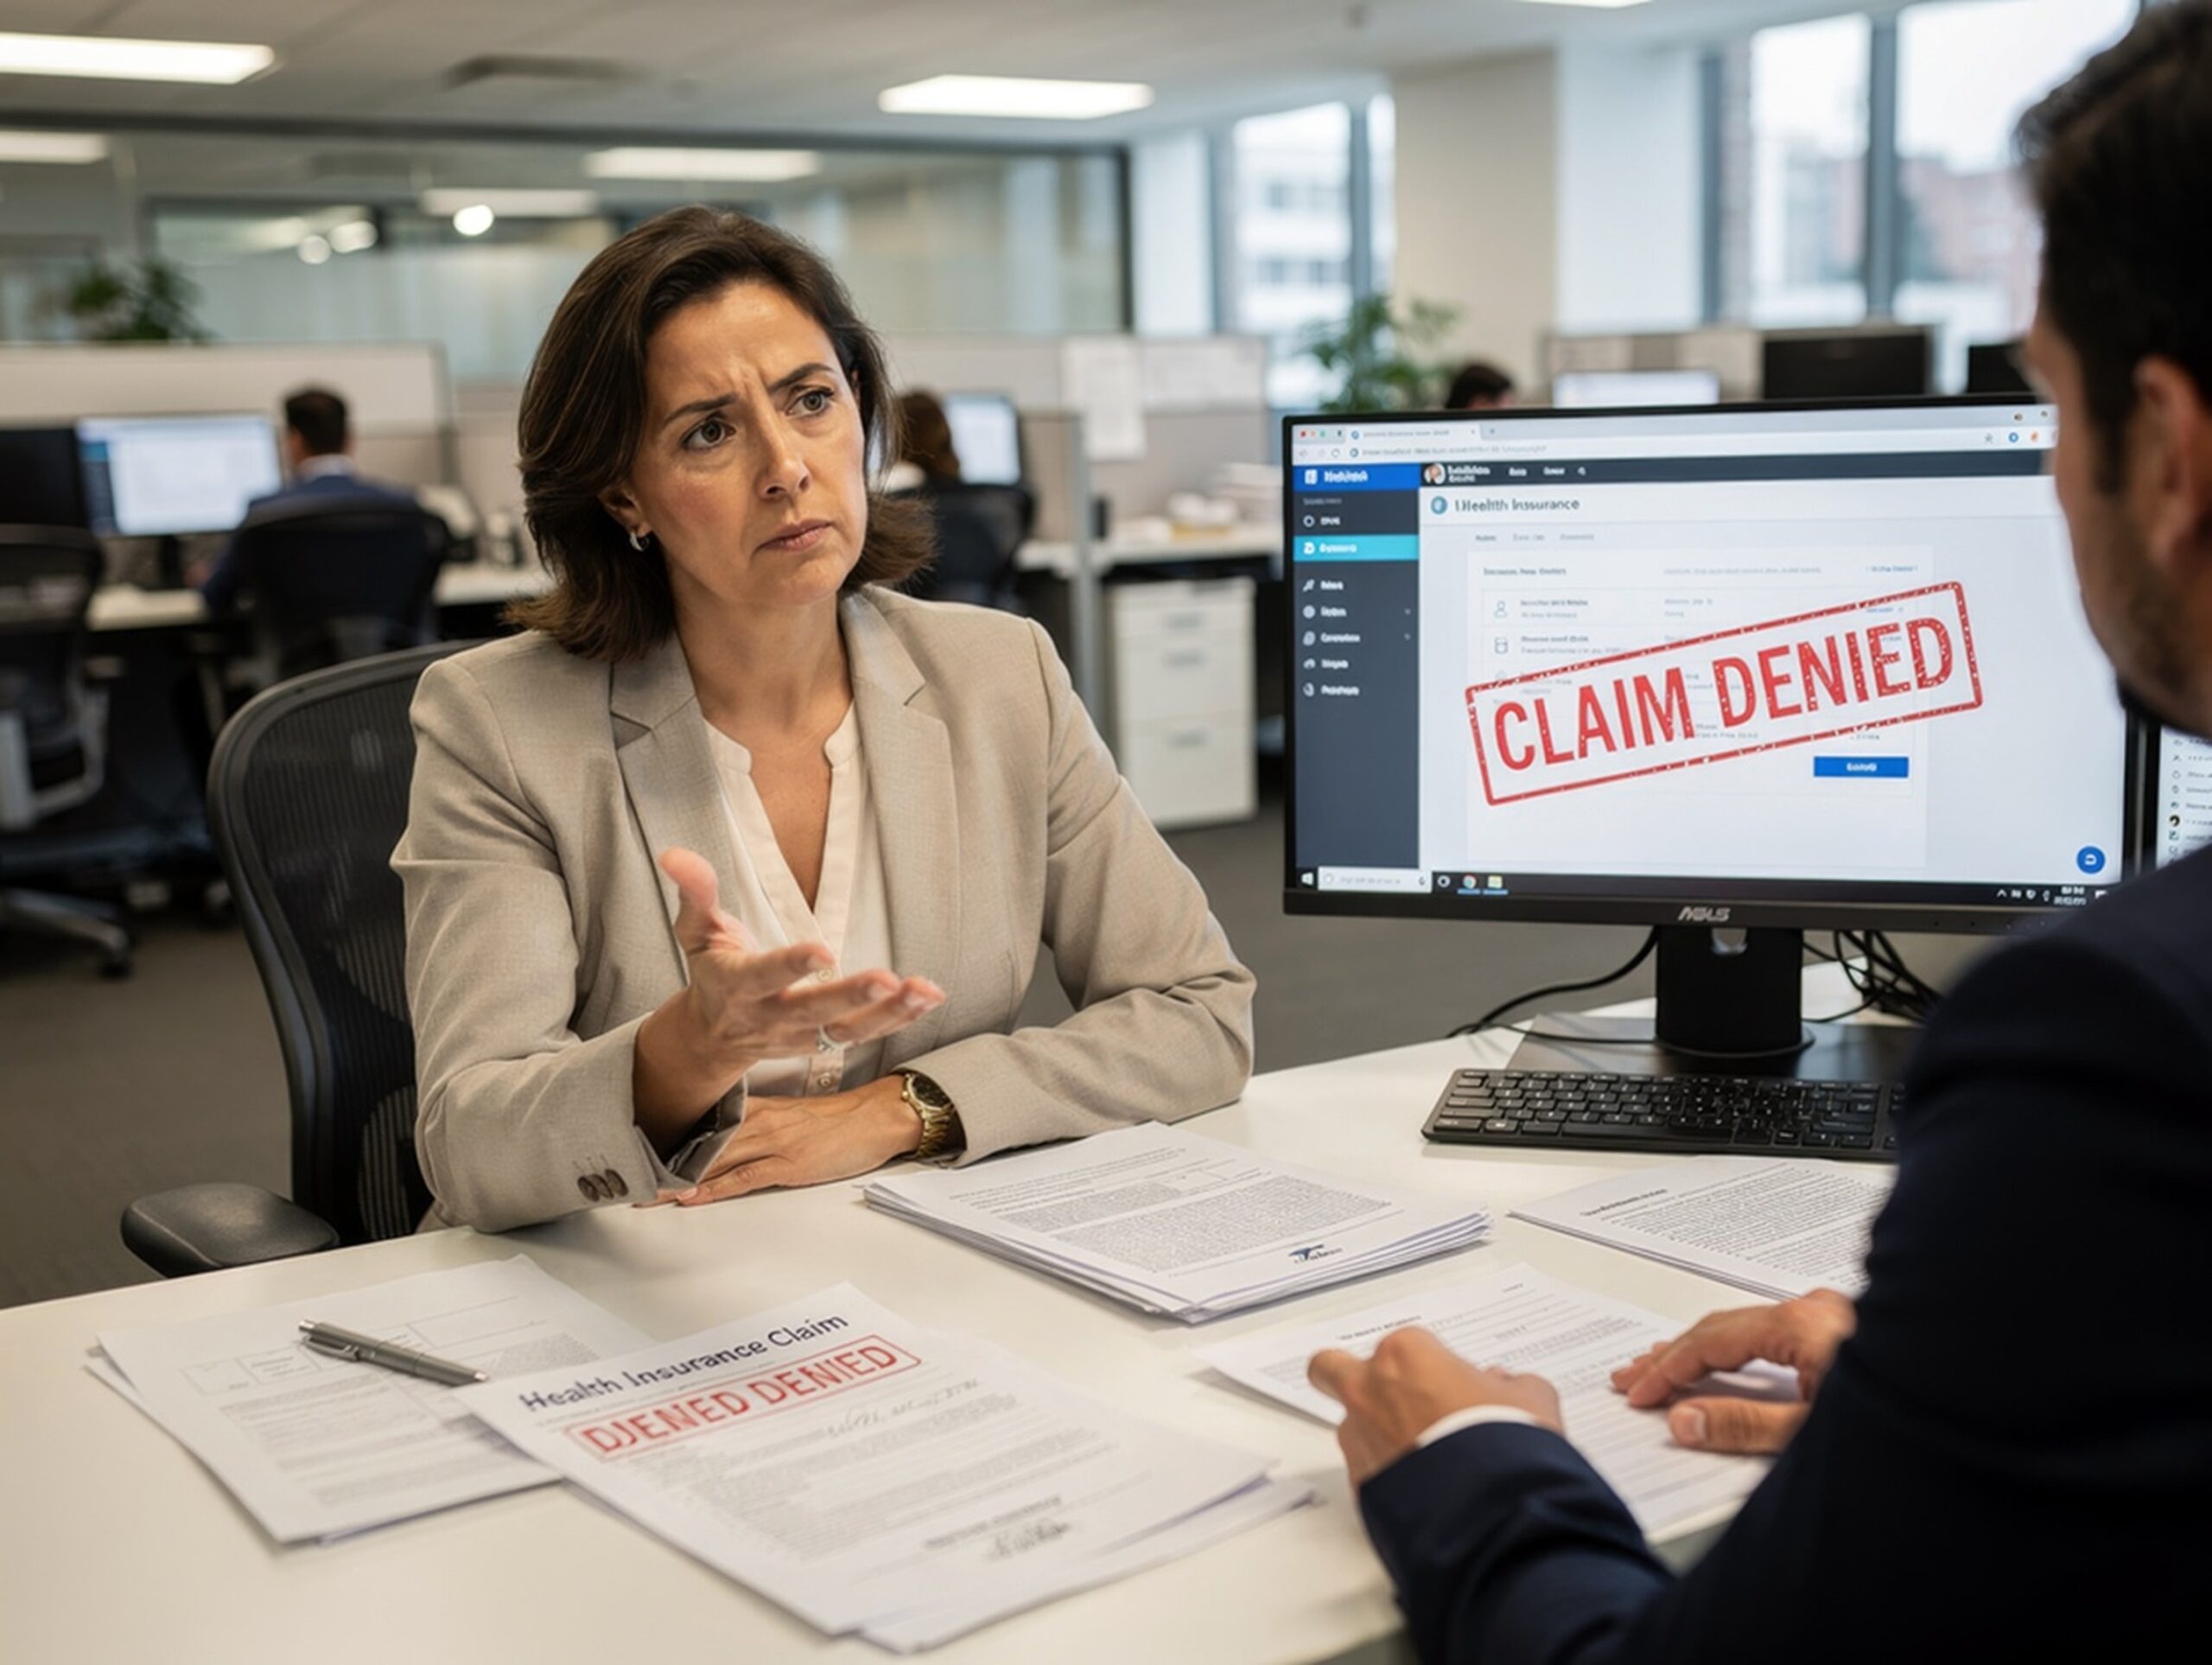
This week, two separate stories from MSN highlight two separate scenarios in which retirees thought they were protecting themselves from Medicaid penalties, only to be tripped-up by the five-year lookback rules. One case involved placing a home in a trust, while the other related to gifts made by a loving grandfather to his grandkids. Each one represents a cautionary tale.
For the sake of brevity, we’ve combined these two stories into one Blog article. The bottom line, however, is clear: make certain you consult with an experienced professional if Medicaid benefits are part of your retirement plan.
IRS Rules and Medicaid Regulations Are Not the Same
The first MSN article for our consideration was written by reporter Jake Fitzgerald. In this instance, a loving grandfather gave each grandchild $19,000 – the maximum allowable under IRS rules without incurring gift taxes – then suffered a stroke the following year. Medicaid counted every dollar the man had gifted, Fitzgerald reports, and then handed the nursing home bill back to the family
“A widower in his late seventies is careful with money and proud of his family,” Fitzgerald writes. “In the year before his stroke, he writes a check to each grandchild for $19,000, the 2026 IRS annual gift tax exclusion.” This man checked with his accountant to confirm that, as long as the gift stays within allowable range, no gift tax return would be required.
“It’s exactly the kind of transfer millions of grandparents make every year,” Fitzgerald notes.
Medicaid Lookback Starts When Application for Care is Filed
Fitzgerald’s MSN article provides a shorthand version of what came next.
“Then comes the stroke,” he writes, “then the rehab hospital, then the nursing home, then the Medicaid application. The state opens its five-year lookback, sees every check, and imposes a transfer penalty.”
Simply put, what that means, the article explains, is that those gifts triggered a Medicaid penalty period. Medicaid will not pay the nursing home during the penalty period, so the bill lands squarely back in the lap of the family.
“Medicaid Doesn’t Care” That Applicant Complied with IRS Rules
The fact that this grandfather was adhering to IRS rules makes no difference, says Fitzgerald. “[T]he IRS annual exclusion and Medicaid’s transfer rules are two completely unrelated systems,” he states, “and staying inside one does nothing to protect you from the other.” He calls this discrepancy “the collision at the heart of long-term care planning.”
Fitzgerald explains the perspective many seniors probably share. “The IRS annual exclusion is a federal gift tax rule, that governs when a donor must file a gift tax return,” he writes. “For tax year 2026 the exclusion remains $19,000 per recipient.” Because gifts at or below that amount require no return at all, the $19,000 threshold “feels like permission” to give with impunity.
Unfortunately, Fitzgerald writes, Medicaid doesn’t care.
“Its transfer rules exist to prevent applicants from giving away wealth to qualify for a needs-based benefit,” he says. “There is no small-gift exception that mirrors the IRS exclusion. Birthday checks, holiday checks, help with a grandchild’s tuition, and a down payment on a first house are all uncompensated transfers in the Medicaid analysis, whether they generate a tax form or not.”
Placing a House in a Trust Can Leave Beneficiary Unprotected
In the second MSN article on this important topic, the situation is different but the five-year lookback still kicks in. The result in this second case left a family shouldering two years of self-pay while the lookback period ran out. This second article was written by Gerelyn Terzo.
She writes, “Picture a widower who moved his paid-off house into a properly drafted irrevocable Medicaid trust at 74. The plan was drawn up with an elder law attorney and it was methodical: avoid sending the home to probate, and upon expiration of the 60-month look-back, before turning 80, ensure the transfer does not disqualify him from Medicaid.”
As Terzo relates, the trust did protect the house from probate and could have shielded it against other forms of estate recovery. But sadly, three years after placing the home in a trust, this man suffered a stroke.
The Trust Started the Clock, but Two Years Remained
Terzo explains that, following a short hospital stay and a period in a rehab facility, the man required custodial care. However, based on the date of the establishment of the trust, Medicaid denied the claim and the family faced nursing home charges of $10,800 a month.
“The trust was drafted correctly,” Terzo writes. “It just started a clock that had not yet finished running.” The family could have gone ahead and applied for benefits, an application that would have triggered a transfer penalty, but instead chose private-pay until the 60-month anniversary of the deed.
“That bridge stretched roughly two years,” says MSN. “The family could be responsible for $259,200 in nursing home expenses before Medicaid arrives without our patient being penalized for the asset transfer.”
Placing the House in a Trust Represents “a Gift”
Writing in MSN, Terzo says the fact that the home was placed in an irrevocable trust “is exactly what makes the funding of the trust an uncompensated transfer.”
She explains, “Moving a house worth several hundred thousand dollars into the trust for less than fair-market value is, in Medicaid’s eyes, a gift. When someone later applies for institutional Medicaid, the agency reviews every transfer made in the preceding 60 months. A gift inside that window can create ineligibility for nursing-home benefits.”
MSN Articles Explain Five-Year Lookback “in Plain English”
Both MSN articles, the one on personal gifts (by Fitzgerald) and the one on placing a house in a trust (written by Terzo) attempt with some success to provide a clear explanation of the five-year lookback. Both articles remind readers that Medicaid is a joint federal-state program, administered at the state level, which means rules vary meaningfully from one state to the next.
Step one for Medicaid officials, once an application is received, is to look for any transfer of assets.
“When someone applies for long-term care Medicaid,” says Fitzgerald, “the state reviews the sixty months of financial history before the application date, called the lookback window. Any uncompensated transfer inside it, meaning a gift, a check to a grandchild, a car signed over, a house put in a child’s name for a dollar, is flagged as a penalized transfer unless it fits a specific exception.”
Medicaid’s Penalty Period is a Separate Calculation
Determining the penalty period – the time period during which Medicaid will not pay long-term care benefits – is a separate calculation, Fitzgerald explains.
“Once the state then calculates a penalty period,” he writes, “it divides the total value of the gifted assets by a penalty divisor, a figure the state sets to represent the average monthly private-pay cost of nursing home care in that state. The result is a number of months during which Medicaid will not pay for care.” Every state uses a different divisor, updated regularly.
In Terzo’s article, she notes that five years is not necessarily the “penalty period.”
“The 60-month look-back only decides which transfers Medicaid examines,” she writes. “The penalty itself is a separate calculation: the uncompensated transfer amount divided by the state’s average private-pay nursing-home rate, which produces a number of months of ineligibility.”
Lookback Timing is “Cruel” Because it Starts When Need is Greatest
Both MSN articles emphasize an essential point, one that (in Fitzgerald’s words) “families never see coming.”
He explains, “The penalty period does not run while the applicant is healthy and living independently. It begins when the applicant is otherwise eligible and already in the nursing home needing care. The clock starts precisely when the bills are largest, and Medicaid pays nothing until the clock runs out.”
Terzo adds, “Under federal rules, that penalty period generally starts…once the applicant is institutionalized, has applied, and would otherwise qualify for Medicaid.” In the case her article describes, timing was key.
“The trust started a five-year clock at 74,” Terzo relates. “The stroke arrived at 77, and long-term care charged the family for every month between the two. Timing the paperwork is [critical in] estate planning.”
Families Can Still Take Action Even When Benefits Delayed
Even a negative response from Medicaid – or the fear of one – doesn’t leave families without recourse. The most important thing is to talk with a professional who knows the rules.
“Not every transfer counts against an applicant,” says Fitzgerald. “Gifts made for fair market value in return, meaning the applicant received something of equal worth, are treated differently from outright gifts. Certain transfers to a spouse, to a blind or disabled child, or into specific kinds of trusts are protected under federal Medicaid rules, with state-level variation on the details.”
He also says that a denial notice may not be the last word. “Every state runs an undue hardship waiver process for situations where the penalty would deprive the applicant of necessary care and the assets truly cannot be recovered. The state’s math itself can be wrong, and denials can be appealed.”
Before You Make Financial Decisions, Ask the Right Questions
Fitzgerald concludes with important advice.
“The right question in your seventies or eighties is whether you could need long-term care within five years,” he cautions. “An elder law attorney licensed in your state can price that risk against your assets before a check is written, or work to unwind one after the fact.”
Medicaid operates under its own set of stringent rules. With so much at stake, make sure you’re working with a professional advisor who understand how the program works, and knows what’s at stake for you and your family.
Rajiv Nagaich – Your Retirement Planning Coach and Guide
Rajiv Nagaich’s newest program on PBS, called Designing Your Ideal Future, is bringing Rajiv’s powerful message to Americans from coast to coast. This engaging and challenging PBS show is prompting thousands to take a fresh look at the type of planning that will help them succeed in retirement.
In this one-hour PBS special, Rajiv Nagaich takes viewers step-by-step through the principles of creating a retirement plan that truly supports the life you want to live. Instead of generic check-the-box paperwork, Rajiv reveals how to infuse your perspective — your values, goals, and priorities — into every legal document and life plan component so your plan becomes a living system for your future.
Designing Your Ideal Future includes insights from real-world planning examples and a live Q&A with Rajiv Nagaich that answers viewer questions about retirement planning, legal readiness, and family communication. It’s perfect for anyone approaching retirement, currently retired, or responsible for a loved one’s future care — and for those who want a clear, effective approach to planning that prioritizes personal choice and quality of life.
What About You?
You’ve heard Rajiv say it repeatedly: 70 percent of retirement plans will fail. If you know someone whose retirement turned into a nightmare when they were forced into a nursing home, went broke paying for care, or became a burden to their families – and you want to make sure it doesn’t happen to you – then these materials are your key to retirement success.
Visit your local PBS station’s schedule to find airtimes and learn how to access companion resources — including a free Legal Readiness Quiz and tools to help build your complete LifePlanning system.
Don’t remain among the millions of Americans sleepwalking their way into a retirement they never wanted. Instead, your retirement can be the exciting and fulfilling life you’ve always hoped it would be. Start by watching, reading and sharing Rajiv’s important message.
And remember, Age On, everyone!
The post Medicaid Five-Year Lookback: Two Scenarios, Two Denials appeared first on Home.
