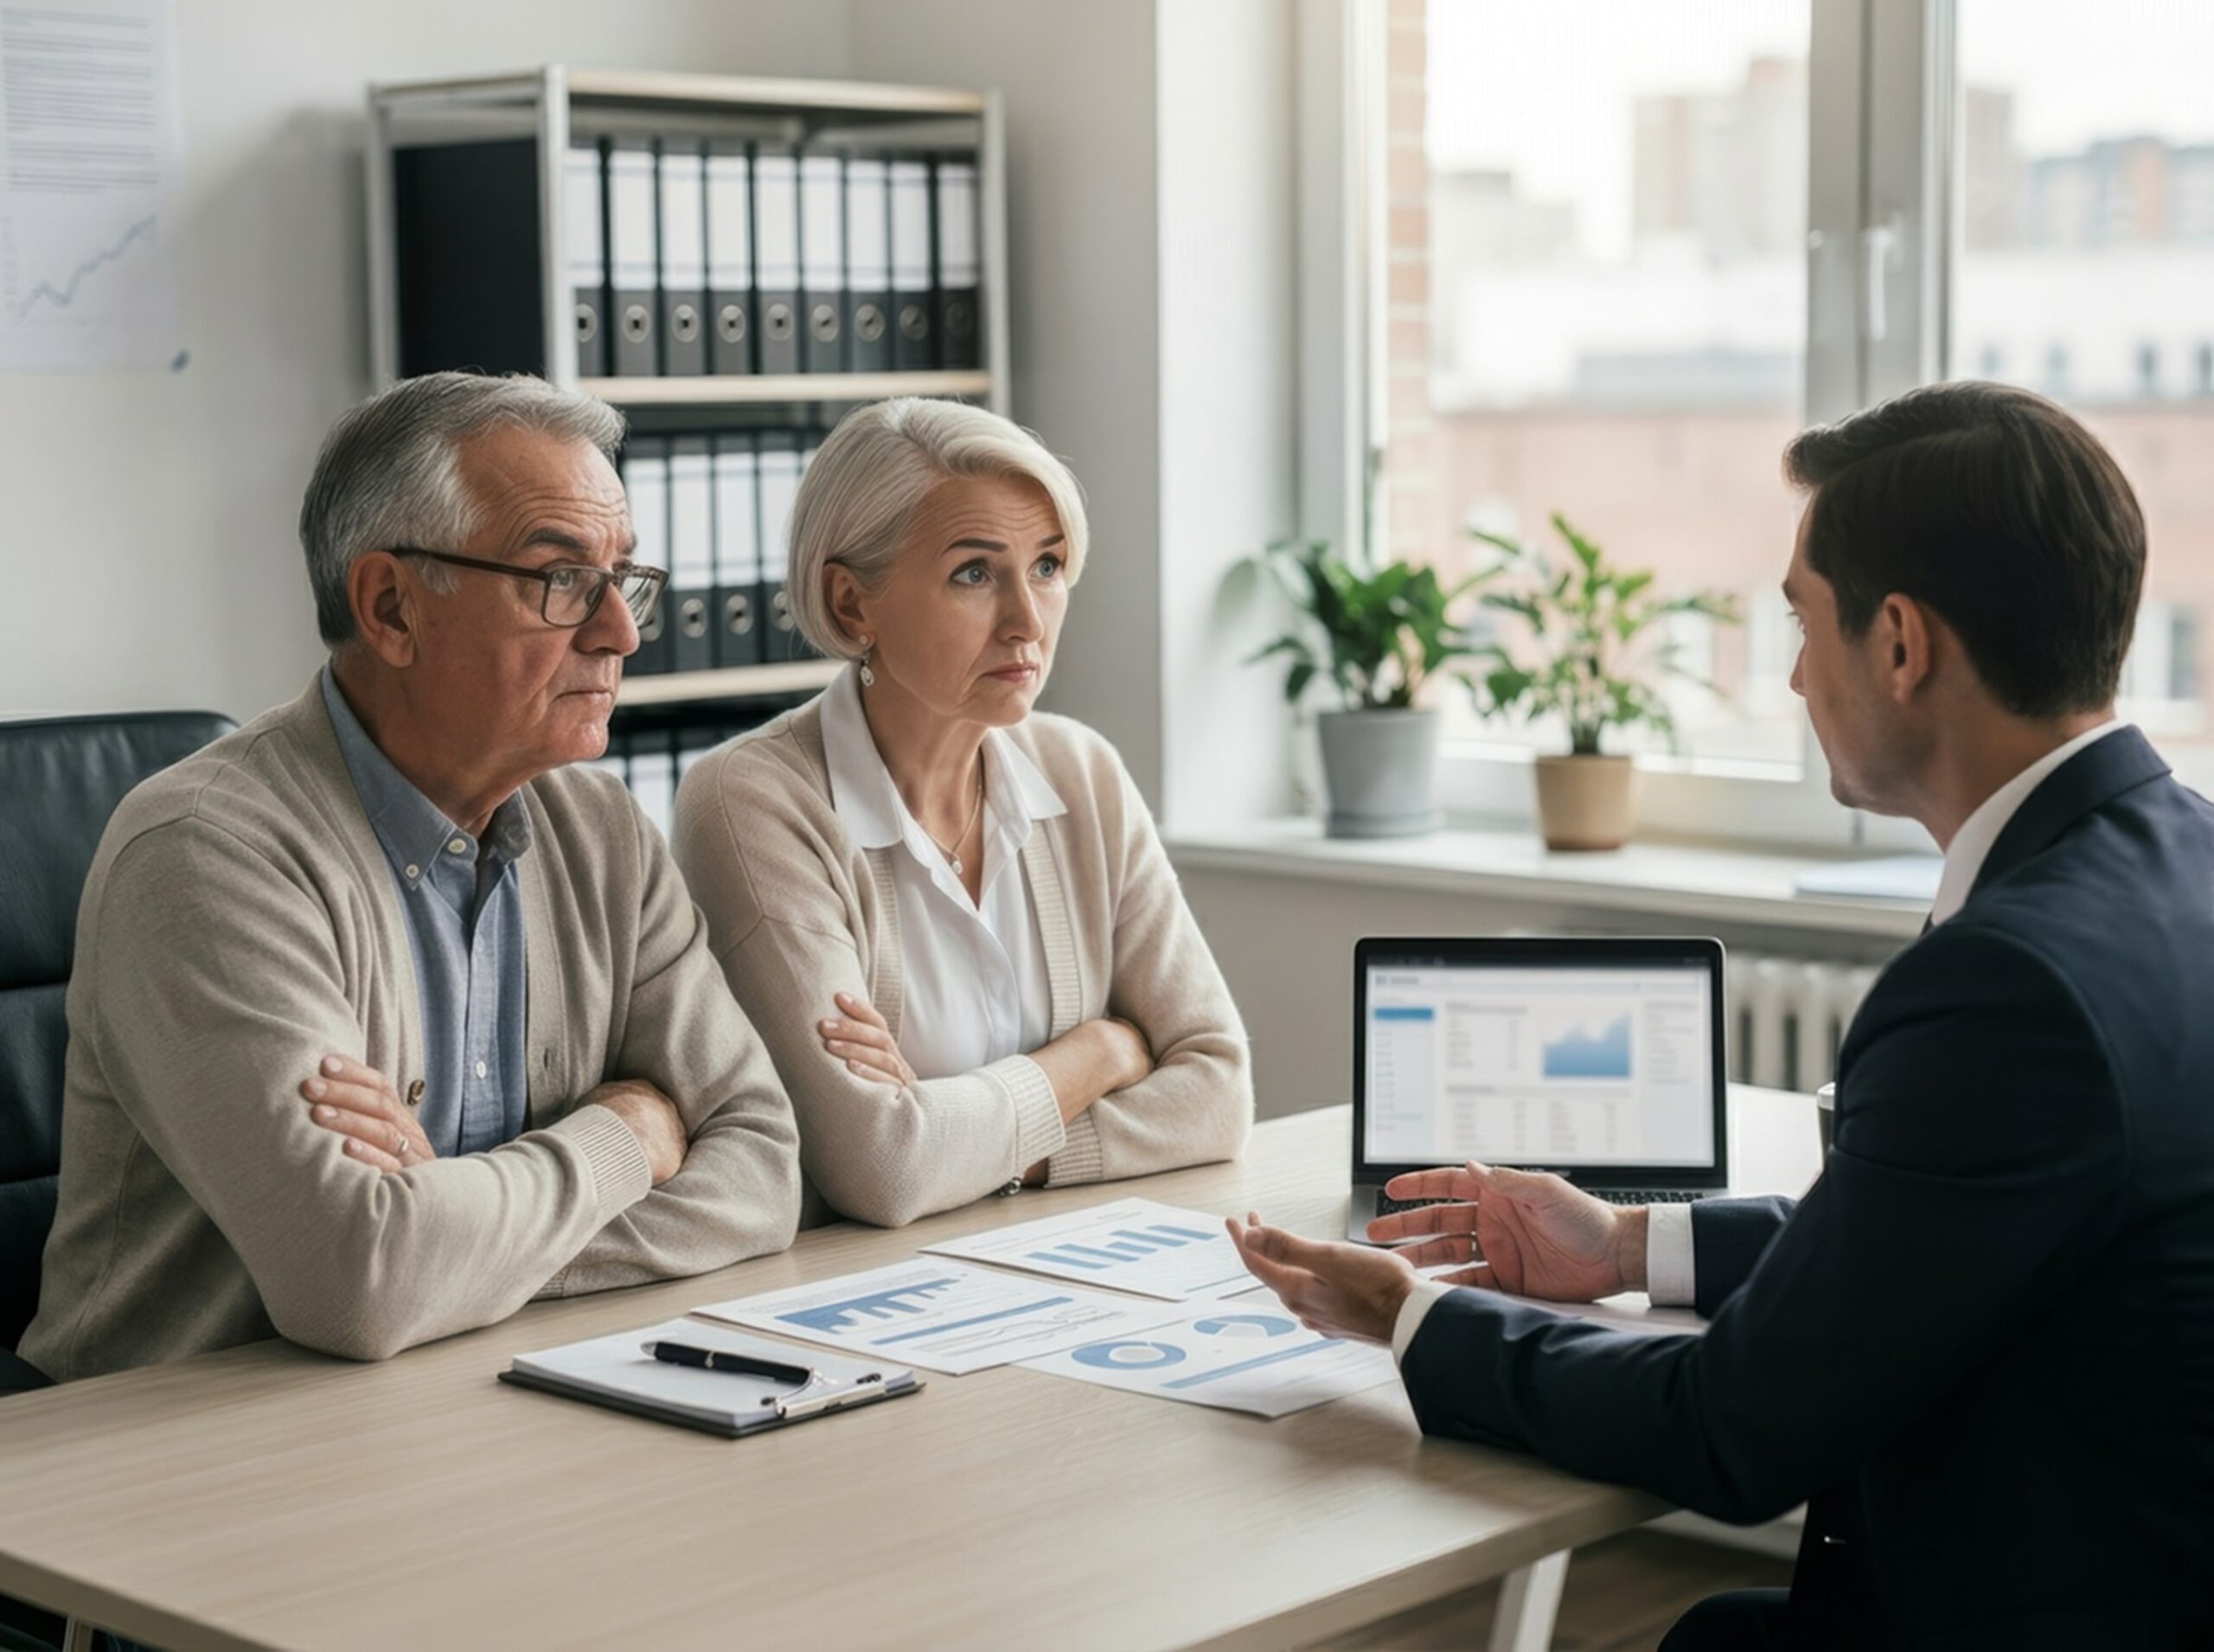
By now, if you’ve been exposed to the basic philosophy that undergirds LifePlanning, you’ve come to realize just how much the planning approach practiced by Rajiv Nagaich diverges from the traditional financial and estate planning industry.
This week on the Blog, we’re offering a pair of articles that attempt to show the extent of those diverging views. One article reflects the LifePlanning approach pioneered by Rajiv. The other is this article showing what might be called “the other side of the coin” when it comes to financial planning. These two articles reveal what one source called “a stark division in how retirement readiness is defined.”
In short, financial planning (especially planning for retirement) comes down to two vastly different philosophies: a product-driven approach and an outcome-driven LifePlanning approach.
Financial Giant Discusses “the Future of Financial Advice”
In preparing this article for the Blog, we wanted to get a snapshot of the traditional view of financial planning, so we decided to consult one of the industry giants: T. Rowe Price, a massive global investment juggernaut that currently has a breathtaking $1.9 trillion under management. Who better to give us insight into the traditionalist view of financial planning?
Our primary source was this extensive article from the firm, published a few months back, and written by T. Rowe Price retirement strategist Rachel Weker. We found the title intriguing: the piece was called, “Understanding the evolving opportunity for financial advice.” The subheading spoke about exploring “the trends shaping the future of financial advice.”
Could it be that traditional financial industry voices are arguing for a more holistic, less product-driven approach to financial planning? A quick review of the article left us skeptical. (Note that we had to edit Weker’s article extensively, but we feel we captured the essence of T. Rowe Price’s corporate approach.)
“Holistic” Language Seems to Signal a Change in Philosophy
Weker begins on a seemingly encouraging note.
“Financial advice has traditionally been viewed through an investment lens,” she writes, “with asset allocation, rebalancing, and investment selection seen as the main drivers of success. Yet as financial lives have grown more complex, it’s become clear that investment recommendations are only one part of a much larger picture.”
So far, so good. In her article, Weker notes that today’s clients are seeking “a more comprehensive and personalized advice model” that will help them with everything from tax and Social Security planning to “health care and lifestyle decisions.”
She adds, “Put simply, financial advice is evolving into holistic lifetime guidance.” Is Weker reading from Rajiv’s LifePlanning playbook?
Examples of “Holistic” Planning Still Show Relentless Focus on Rates of Return
Weker’s article then goes on to provide some examples of what her firm considers “holistic” planning. She calls this “the case for a more comprehensive advice model.”
However, a closer look at her examples still reveals a focus that is overwhelmingly money-focused. One graph shows how the financial priorities of clients shift over time. The seven categories all involve saving and spending: regular expenses, emergencies, buying a home or other major purchase, education costs, health care costs, and retirement.
As one might expect, different generations show differing priorities. Yet in Weker’s article, this basic and common-sense fact is touted as apparent evidence of a more “holistic” advising model. We’re not convinced.
Corporate Definition of “Holistic” Still Seems One-Dimensional
Later in her article, Weker relates how another piece of research by T. Rowe Price reveals competing priorities among clients.
“In our 2025 study of workplace retirement savers and retirees,” she writes, “savers ranked short- and medium-term priorities, including building emergency savings and buying a home, closely alongside retirement objectives. Helping individuals strategically navigate these competing priorities—rather than allowing them to crowd out long-term retirement goals—is a defining benefit of holistic advice.”
Once again, Weker’s definition of “holistic advice” seems far narrower than we would expect. Helping a client prioritize different “savings buckets” is a pretty traditional approach to financial planning. In our view, it doesn’t rise to the level of “holistic” planning.
What Does “Holistic” Actually Mean?
Since the word “holistic” seems to be getting used a lot in this article, we figured a definition would be in order. So, we asked our AI assistant, Google’s Gemini, to give us one.
According to Gemini, the term “holistic” refers to an approach that looks at a system as a whole, rather than just focusing on its individual parts. It is based on the principle that the components of a system are intimately interconnected and can only be truly understood by looking at the entire picture. A holistic view acknowledges that a change in one area will naturally impact another.
Rajiv Nagaich’s LifePlanning strategy applies holistic thinking to all five of the key elements in retirement planning: health coverage, housing choices, legal issues, family dynamics, and – of course – finances. In our view, except for financial concerns, all of these are conspicuously absent from the T. Rowe Price definition of “holistic” planning. But let’s continue on.
Holistic Financial Planning Should Give Clients Peace of Mind
The T. Rowe Price article seems to get a bit closer to the “holistic” mark as we read further.
Weker makes the case that longer life expectancy and the need to manage defined contribution plans (as opposed to the predictability of pensions) have made retirement decision-making more complex. She asserts that an approach that is truly holistic is needed to cover all the variables in today’s confusing retirement landscape.
Weker notes that over half of retirees surveyed by T. Rowe Price worry about longevity risk, and how to plan for costs of health care and long-term care. Roughly the same percentage said “they rely on a financial advisor for retirement income information.”
But once again, the emphasis in the data is on “withdrawal strategies, income solutions, and health care planning” – financial solutions, not plans that are truly holistic and multi-dimensional.
Retirement “Peace of Mind” is Entirely Related to Financial Measures
In another graph in Weker’s article, survey respondents were asked what factors would give them confidence in their ability to retire. All five of the top responses were financially focused.
They included adequate savings; reliable income; freedom from major debt; growing investments; and money for medical expenses. In this survey, “financial peace of mind in retirement” as defined by T. Rowe Price is 100 percent linked to financial outcomes.
We did encounter one interesting bit of data. The study cited by Weker in her article revealed that, among retirement savers who work with a financial advisor, nearly 60 percent had made “a serious effort” to plan for nonfinancial aspects of retirement, “such as lifestyle, psychological, and emotional considerations.” Sadly, however, the article didn’t go into further explanation of this topic.
Our Prediction: the Financial Industry Will Remain Money-Focused
Our purpose in this brief examination wasn’t to single out any one financial planning firm. We suspect the theme of the T. Rowe Price analysis – emphasizing the need for financial planning that is “holistic” – reflects a sincere desire to offer comprehensive services to clients.
Still, however, the language of the Weker article betrays a singular focus on finances. There’s little if any mention of housing concerns, family dynamics, or legal preparedness, and only a glancing mention of health care, focused solely on costs.
We’ll cite three quotes from the article as closing examples:
Industry View: “For advice to be truly impactful, it must evolve alongside an individual’s needs, connecting to and balancing all aspects of their financial life—from saving and investing to income generation, tax optimization, health care funding, and legacy planning.” LifePlanning View: “Individual needs” are not the same as financial needs.
Industry view: “The next generation of retirement advice is poised to be more comprehensive and more focused on individual needs. As participants and retirees look to make interconnected decisions across all areas of their financial life, the retirement ecosystem has an opportunity to respond with compelling services and solutions.” LifePlanning View: So-called “interconnected decisions” go far beyond our financial life.
Industry view: “Technology will play a pivotal role in this effort, but no single tool can address an individual’s unique financial challenges, preferences, and aspirations. Human understanding and holistic service will be central to the advice experience.” LifePlanning View: as long as planners focus only on finances, their services can never be truly called “holistic.”
Rajiv Nagaich – Your Retirement Planning Coach and Guide
Rajiv Nagaich’s newest program on PBS, called Designing Your Ideal Future, is bringing Rajiv’s powerful message to Americans from coast to coast. This engaging and challenging PBS show is prompting thousands to take a fresh look at the type of planning that will help them succeed in retirement.
In this one-hour PBS special, Rajiv Nagaich takes viewers step-by-step through the principles of creating a retirement plan that truly supports the life you want to live. Instead of generic check-the-box paperwork, Rajiv reveals how to infuse your perspective — your values, goals, and priorities — into every legal document and life plan component so your plan becomes a living system for your future.
Designing Your Ideal Future includes insights from real-world planning examples and a live Q&A with Rajiv Nagaich that answers viewer questions about retirement planning, legal readiness, and family communication. It’s perfect for anyone approaching retirement, currently retired, or responsible for a loved one’s future care — and for those who want a clear, effective approach to planning that prioritizes personal choice and quality of life.
What About You?
You’ve heard Rajiv say it repeatedly: 70 percent of retirement plans will fail. If you know someone whose retirement turned into a nightmare when they were forced into a nursing home, went broke paying for care, or became a burden to their families – and you want to make sure it doesn’t happen to you – then these materials are your key to retirement success.
Visit your local PBS station’s schedule to find airtimes and learn how to access companion resources — including a free Legal Readiness Quiz and tools to help build your complete LifePlanning system.
Don’t remain among the millions of Americans sleepwalking their way into a retirement they never wanted. Instead, your retirement can be the exciting and fulfilling life you’ve always hoped it would be. Start by watching, reading and sharing Rajiv’s important message.
And remember, Age On, everyone!
The post Industry Giant Says Financial Advice is “Evolving” – but Is It Really? appeared first on Home.
