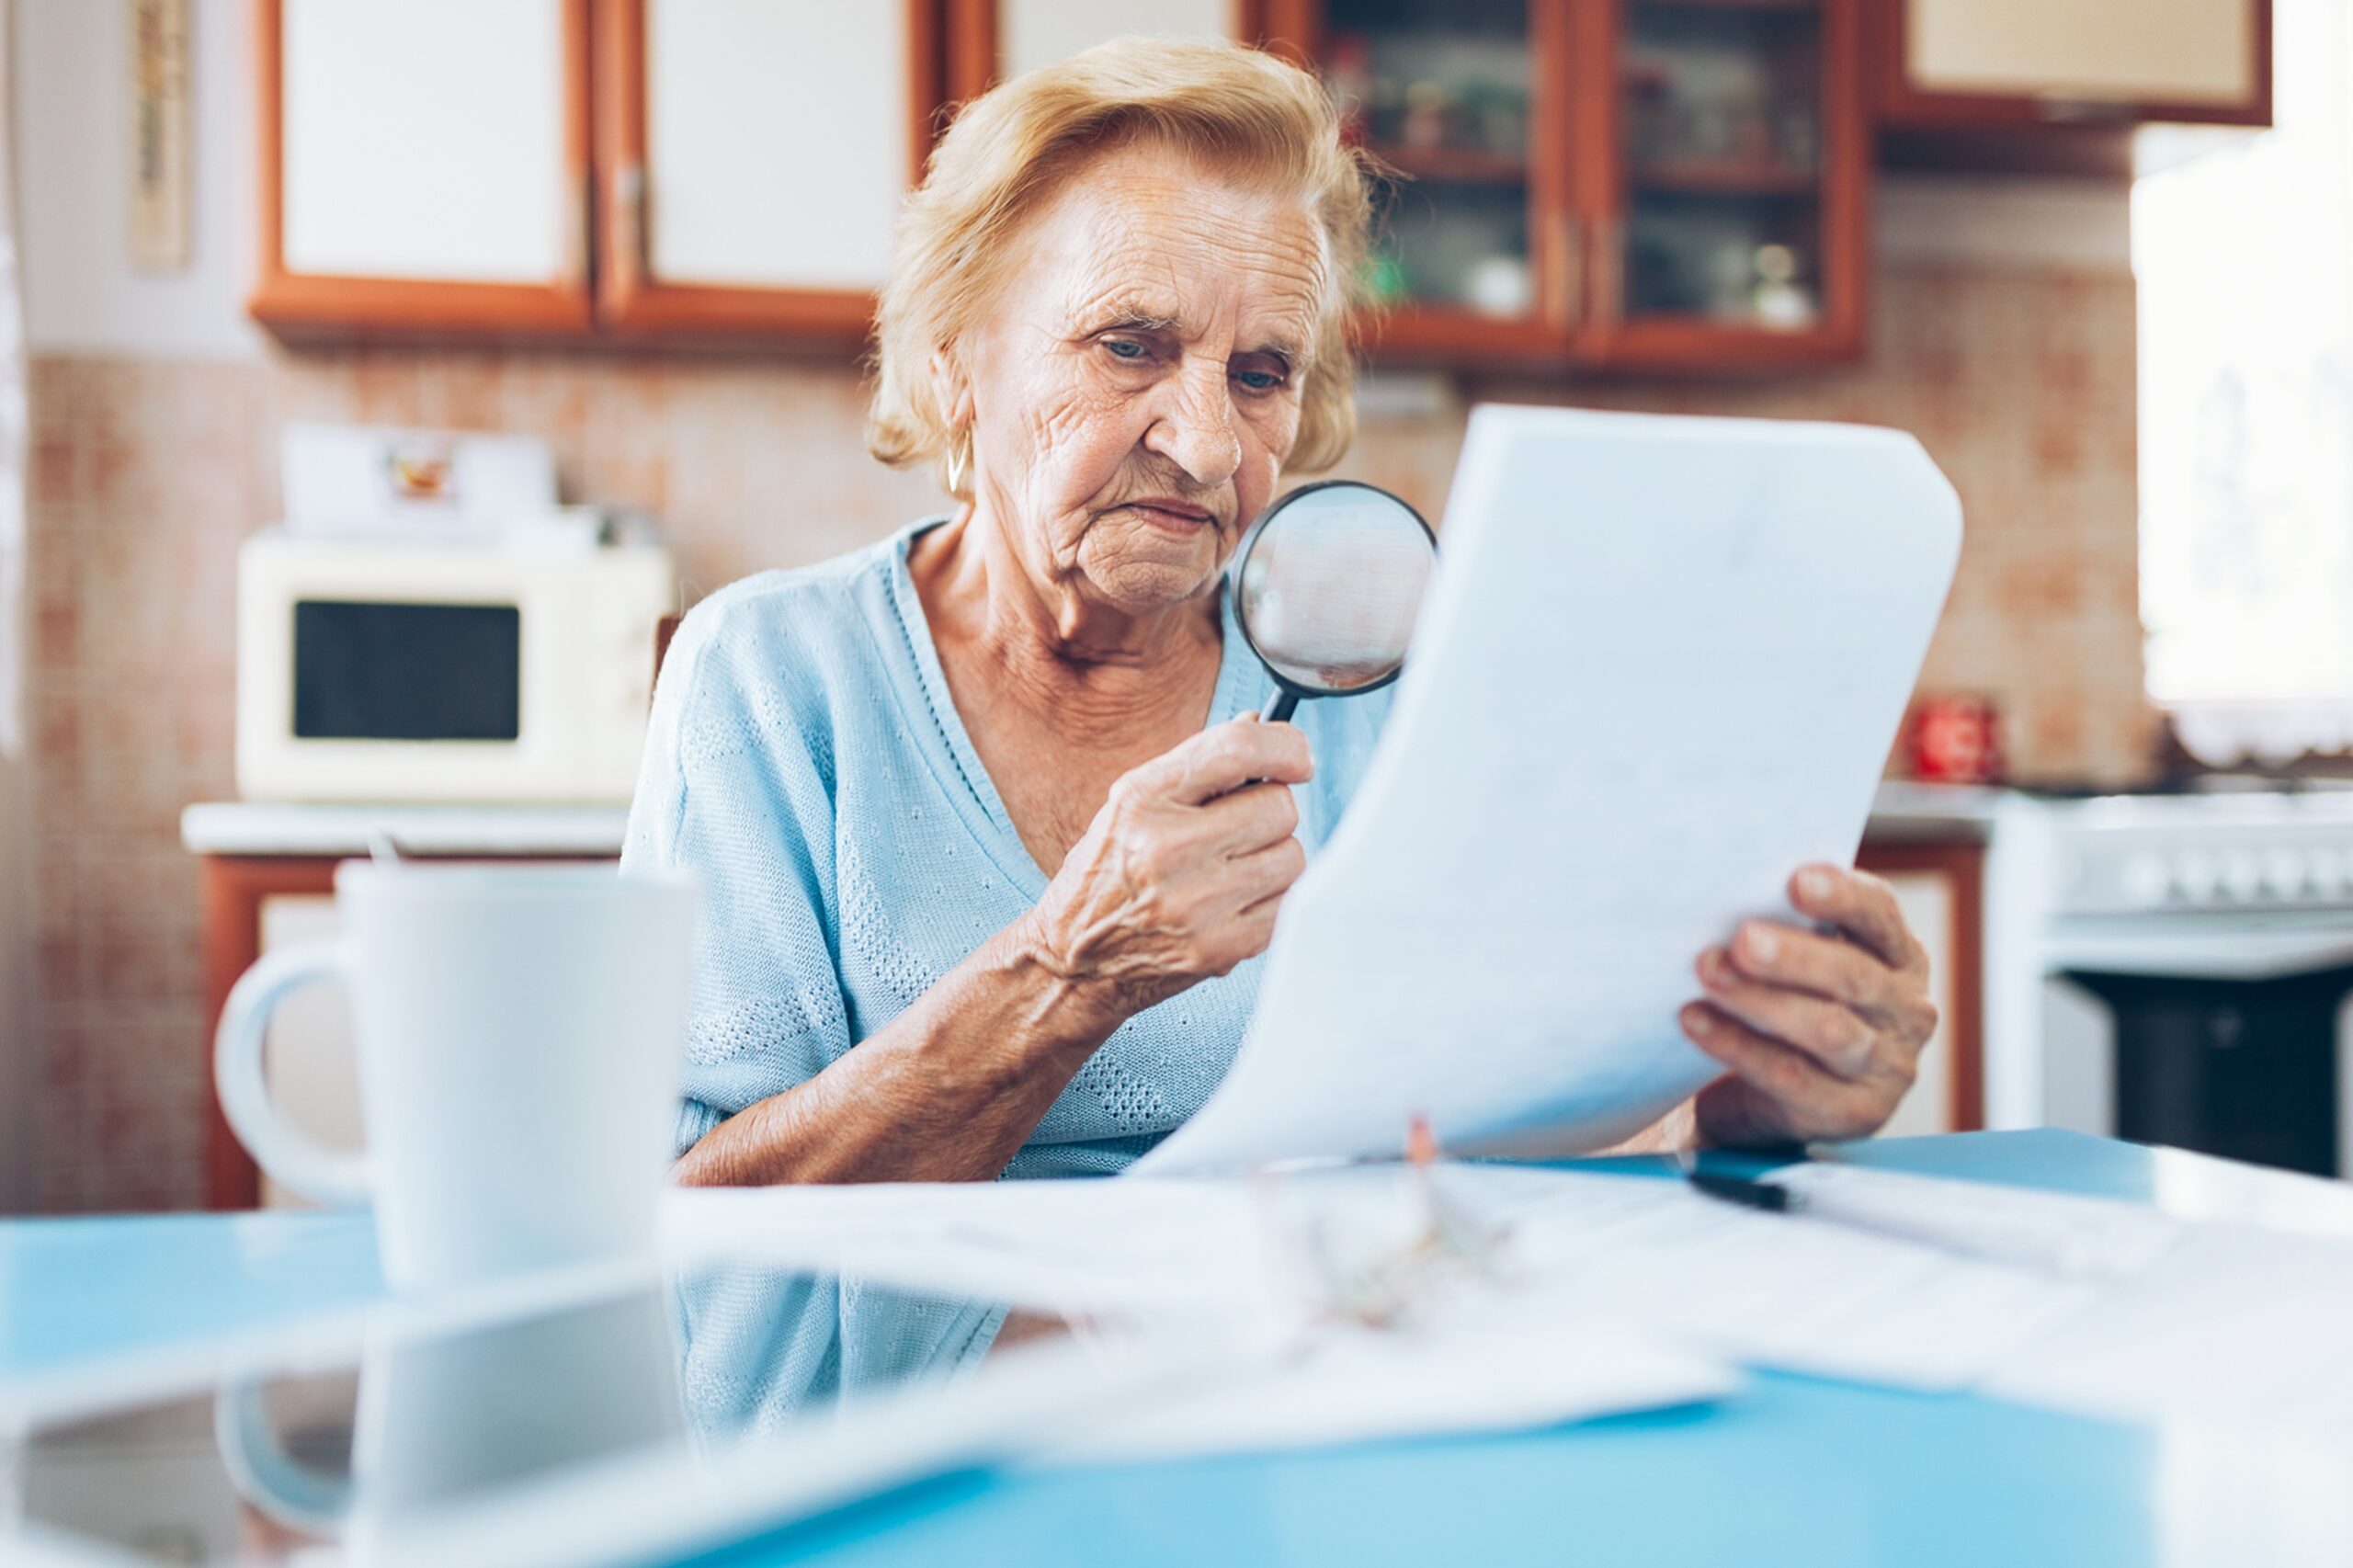
If you are a Medicare Advantage beneficiary, an essential document should have arrived in your physical mailbox or email inbox recently. Insurers are required to deliver your Annual Notice of Change (ANOC) by September 30 each year. This statement provides a clear overview of upcoming plan modifications so you can make informed decisions before Medicare Open Enrollment begins.
Healthcare experts strongly caution beneficiaries against ignoring, discarding, or deleting this document. Studies indicate that approximately 70 percent of beneficiaries ignore Open Enrollment completely each year. However, reviewing this notice remains critical for anyone enrolled in Medicare Part D or a Medicare Advantage plan, as it helps protect both your health and your household budget.
As reporter Donna LeValley highlights in a detailed piece for Kiplingerfrom 2025, examining your ANOC ensures you remain aware of shifting costs and network alterations. The original Kiplinger guidance offers timely reminders as Medicare Open Enrollment approaches on October 15th. Paying close attention to these updates helps prevent unexpected fee increases or loss of access to preferred medical providers.
(Editor’s Note: The source article from Kiplinger has been updated for 2026, though the core recommendations regarding the Annual Notice of Change remain the same.)
Why You Shouldn’t Leave Your Health Insurance on Autopilot
Kiplinger’s advice is clear. If you have not yet examined your Annual Notice of Change (ANOC) letter from Medicare, set aside time to review it immediately. Leaving your health coverage unchanged without evaluating yearly updates can lead to costly surprises.
“If you have a Medicare Part D or Medicare Advantage Plan, this document is crucial,” LeValley writes. “The information inside will help you decide whether to keep your current coverage or find a new plan for the coming year. Don’t make the mistake of keeping your plan on autopilot without reviewing it first.”
Essential Information for Medicare Advantage and Part D Policyholders
This mandatory annual communication gives policyholders an explicit preview of their plan’s upcoming cost structures, prescription coverage, and provider availability for the new calendar year.
“The arrival of the new notice is an opportunity to consider whether your current Part D drug plan or MA plan is still the best way to receive the care you need at a price you can afford,” LeValley explains. “If not, it may be time to change plans.”
If you did not receive your ANOC document by the end of September, contact your plan provider directly to request an additional copy via mail or electronic delivery.
Key Coverage Details Outlined in the Annual Notice of Change
The ANOC directly compares your existing benefits against next year’s terms, spotlighting every critical modification. Understanding these specific areas ensures you know exactly what questions to evaluate during your review.
Out-of-Pocket Cost Adjustments: The notice outlines updates to monthly premiums, annual deductibles, copayments, and coinsurance amounts for clinical visits and hospitalizations.
Policyholders should ask: For Medicare Advantage plan participants, has your maximum out-of-pocket limit increased? Has the monthly premium changed for your MA or Part D drug plan?
Prescription Drug Formulary Updates: The documentation specifies whether your drug plan’s formulary has changed. Checking if your daily medications remain covered or have been moved to a higher cost tier is essential to preventing unexpected pharmacy expenses.
Policyholders should ask: Are there any coverage restrictions for your medications, such as quantity limits or prior authorizations? How much will you pay for generic and brand-name drugs? Is your pharmacy in the plan’s network? Is it a “preferred pharmacy” that offers the plan’s best pricing?
Doctor and Hospital Network Changes: Insurers frequently alter their networks of participating physicians, specialists, medical facilities, and pharmacies.
Policyholders should ask: Are your current doctors in the network? Are hospitals or specialists you may need in the network? Are you willing to switch to other providers if your preferred choices are not in the network anymore?
Added or Removed Coverage Perks: Your statement details newly added supplemental benefits as well as existing perks that may have been restricted or eliminated. These adjustments frequently impact dental, vision, and hearing coverage.
Policyholders should ask: Will you need a referral from your primary care provider to see a specialist? What new benefits have been added to your plan? What existing benefits have been eliminated from your plan?
How the ANOC Helps You Make Informed Medicare Decisions
Having access to clear coverage details empowers you during the Medicare Annual Enrollment Period (AEP), which runs from October 15 through December 7 annually.
First, reviewing the statement prevents unexpected financial and medical disruptions. “Without reading the ANOC, you could be surprised on January 1 by higher costs, a medication no longer being covered, or that your doctor or preferred facility is no longer in your network,” LeValley writes.
Second, the notice provides actionable insights that allow you to explore alternative options if your current plan no longer fits your budget or medical needs. “You can then switch to a new Medicare Advantage or Part D plan during the AEP that better suits your needs,” LeValley adds. “You can even switch back to original Medicare from an MA plan.”
Third, reading the document gives you direct control over your healthcare strategy for the coming year. “Even if you were happy with your plan this year, the changes outlined in the ANOC might make it less suitable for you next year,” LeValley writes.
Next Steps for Evaluating Your Medicare Coverage
Taking time to review your policy terms ensures you remain prepared before changes take effect at the start of the year.
“Take time to review your plan,” LeValley urges. “You don’t want to be caught off guard by higher costs or coverage changes after January 1. Whether you decide to stay with your current plan or to explore other Medicare coverage options, you want to make that choice based on the facts.”
If you have questions about specific updates outlined in your letter, contact your plan’s customer service team directly for clarification.
For additional unbiased assistance, several official Medicare resources are available to help guide your choices:
To explore alternative options in your local area, visit the Medicare.gov/plan-compare tool to compare health and drug coverage options.
Contact 1-800-MEDICARE (1-800-633-4227) for round-the-clock answers regarding your enrollment options. TTY users can call 1-877-486-2048, or visit Medicare.gov.
Connect with your local State Health Insurance Assistance Program (SHIP) for free, individualized counseling from certified volunteers. In Washington State, home to AgingOptions and Life Point Law, this service is provided by the Statewide Health Insurance Benefits Advisors (SHIBA) through the Office of the Insurance Commissioner.
Retirement Planning Guidance with Rajiv Nagaich
Beyond managing annual Medicare updates, comprehensive long-term planning plays a vital role in securing your financial and personal well-being. Rajiv Nagaich’s PBS special, Designing Your Ideal Future, offers practical guidance to help Americans build resilient retirement strategies.
Throughout the one-hour program, Rajiv explains how to craft a master plan that reflects your personal values, healthcare preferences, and financial goals. Rather than relying on generic legal documents, viewers learn how to align every aspect of their estate and care plans into a cohesive system.
The broadcast features practical planning scenarios alongside a live Q&A session addressing legal readiness, long-term care management, and family communication. It serves as an essential resource for pre-retirees, retirees, and family caregivers seeking clarity and control over future care decisions.
Taking Control of Your Long-Term Retirement Strategy
As Rajiv frequently emphasizes, up to 70 percent of traditional retirement plans encounter severe obstacles due to uncoordinated legal, financial, and housing decisions. Without a structured plan, individuals risk losing independence or exhausting their savings on long-term care.
Check your local PBS station listings for upcoming airtimes and companion materials, including the free Legal Readiness Quiz and LifePlanning development tools. Proactive planning prevents you from navigating retirement unprepared. By making informed decisions about your Medicare coverage today and building a comprehensive long-term plan, you can protect your health, your assets, and your peace of mind.
And remember, Age On, everyone!
The post Has Your Medicare “Annual Notice of Change” Arrived? Don’t Toss It! appeared first on Home.
