What is a Medicare agent? For that matter, what is a Medicare broker? Are they the same or different? And why on earth would I need one?
Here at the Blog, we tend to focus on Medicare every fall during the annual open enrollment period – which runs from October 15 to December 7 – since that’s when the Medicare marketing machine really cranks up as current enrollees have the ability to change plans without penalty.
But Medicare is actually a year-round endeavor here in the U.S., if for no other reason than the fact that thousands of baby boomers are turning 65 every single day and hitting their initial enrollment window. These newly-eligible beneficiaries often find themselves ill-equipped to make one of the most important choices of their retirement years: choosing between Original Medicare and Medicare Advantage.
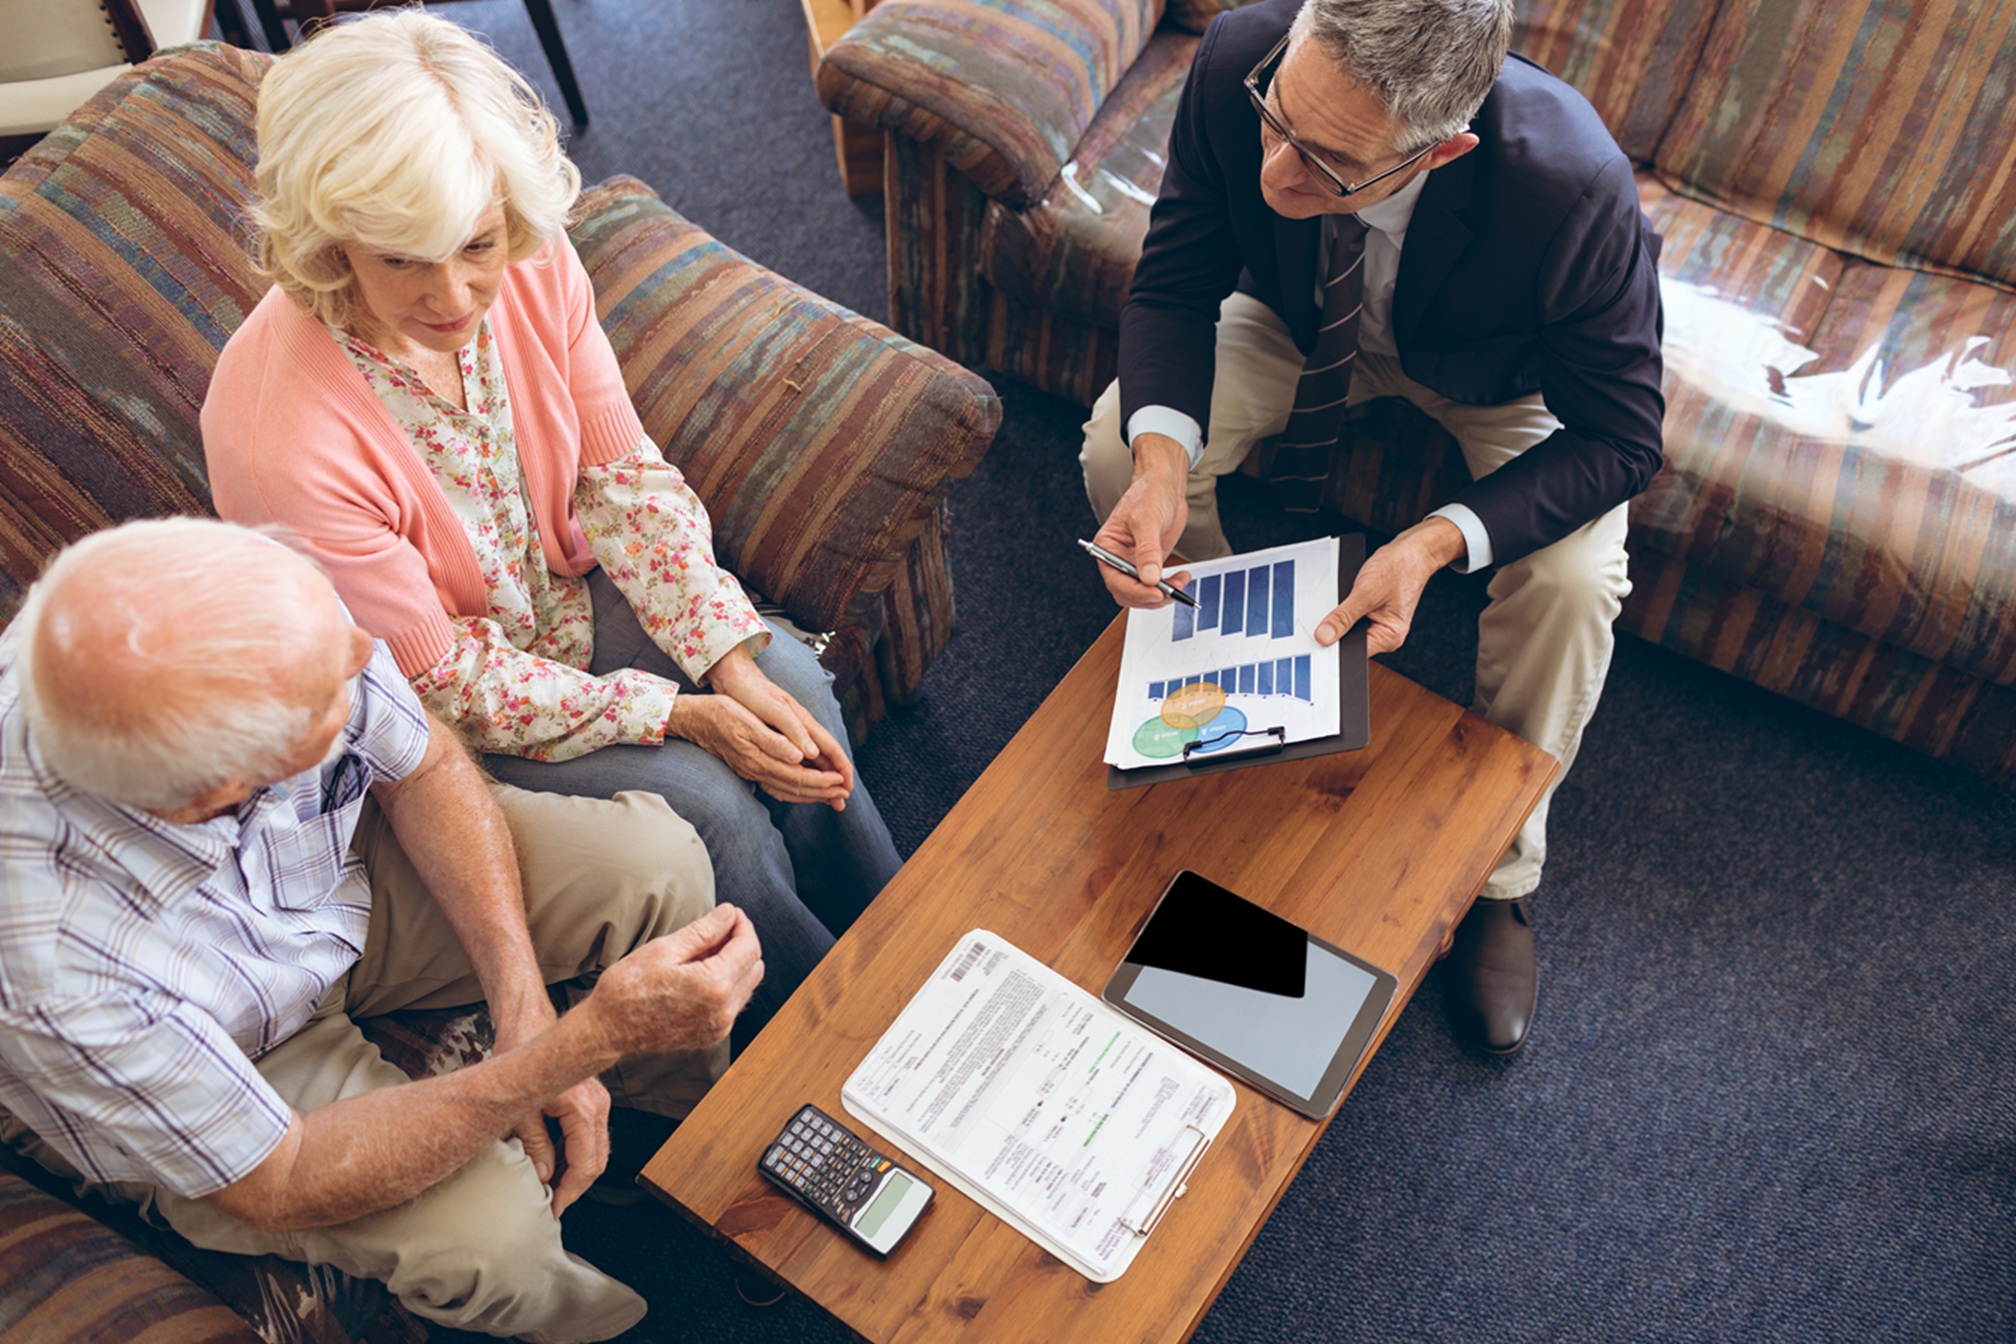
Many will seek out a licensed Medicare agent or broker to guide them through. To help us understand the differences, we’re turning to an updated article from a website we’ve used before, called Verywell Health. It was written by Tolu Ajiboye, a health writer who works with medical, wellness, biotech, and other healthcare technology companies.
Medicare Agents and Brokers: Helping Dispel the Confusion
She begins her article by stating the obvious. “Medicare and its numerous plans can be quite confusing,” she writes. “Friends and online guides can be very helpful but having an expert to guide you in choosing the best plans for your individual needs has its advantages. This is where Medicare agents and brokers come in.”
According to the basic definition, agents and brokers are similar. Captive agents work with one single insurance company selling their specific products, while independent agents and brokers are licensed to write plans with numerous carriers, meaning they have access to a wider variety of plan options.
Beyond that, how have the rules changed—and do you still need one?
Regulatory Changes Have Eliminated a Mandatory Waiting Period
While the basic definitions hold true, federal rules from CMS have changed how these pros operate. First, there used to be a mandatory 48-hour waiting period after you’ve completed what’s called the Scope of Appointment form (SOA) before you meet with a broker or agent. The SOA is a formal agreement that serves as a consumer protection tool, outlining exactly which types of Medicare plans the agent is allowed to discuss during that specific meeting.
Under updated rules from CMS, that waiting period has been removed. You no longer have to wait two days after signing the consent form; agents can now complete this required paperwork and dive straight into a same-day marketing meeting with you.
CMS Has Capped Sales Commissions for New Policies and Renewals
Another regulatory change affects how agents and brokers get paid.
The article used to note that compensation was entirely up to individual insurance company contracts. Now, federal regulations enforce strict commission caps on Medicare Advantage and Part D plans. This ensures that brokers give you truly objective recommendations rather than steering you toward a plan that pays them a higher corporate administrative fee.
For 2027, CMS has set a ceiling of $725 in commissions for agents enrolling new clients in a Medicare Advantage plan. The maximum commission for policy renewals is $363. (These rates are slightly higher in some states.)
An Agent or Broker Can Help You Avoid Medigap Traps
Where an expert really saves you time and effort is navigating the hidden traps of Medigap plans. If you try to purchase a supplemental policy outside of your initial six-month open enrollment window, private insurers will require you to go through medical underwriting.
An underwriter will assess your current state of health, and in some case will boost your Medigap premium. They can also deny you coverage entirely due to pre-existing conditions.
Because most states offer no annual guaranteed-issue window to switch Medigap plans, you could find yourself locked out of supplemental coverage if you drop Medicare Advantage. A savvy broker is essential to help you evaluate your current coverage and see if you can realistically meet those strict underwriting guidelines.
Medicare Agents and Brokers: How Do You Choose?
The assistance of a Medicare agent or broker costs you absolutely nothing, but Ajiboye notes you should look for a few specific things when selecting one. Always check that they are licensed in your state and ask for contactable references.
Most importantly, watch out for plan specialization. It used to be that some brokers only focused on Medigap, but today, many focus exclusively on enrolling people in Medicare Advantage plans. If Original Medicare plus a Part D drug plan and a Medigap policy would actually be the best fit for your budget, an Advantage-only agent won’t present those options to you.
It’s highly recommended to find an independent broker who sells all three private coverage types and can explain the pros and cons objectively.
Unbiased Help Available from Volunteer Advisors – but Don’t Wait
You can use the national State Health Insurance Assistance Program search tool to find help locally. For assistance within the State of Washington, home to AgingOptions and Life Point Law, visit the Office of the Insurance Commissioner’s website to connect with the free, unbiased Statewide Health Insurance Benefits Advisors (SHIBA) program, which lists volunteer offices in every county.
But with Open Enrollment well underway, you need to act quickly to secure an appointment with an advisor. You don’t want to delay and be forced to rush such an important decision.
Rajiv Nagaich – Your Retirement Planning Coach and Guide
Rajiv Nagaich’s newest program on PBS, called Designing Your Ideal Future, is bringing Rajiv’s powerful message to Americans from coast to coast. This engaging and challenging PBS show is prompting thousands to take a fresh look at the type of planning that will help them succeed in retirement.
In this one-hour PBS special, Rajiv Nagaich takes viewers step-by-step through the principles of creating a retirement plan that truly supports the life you want to live. Instead of generic check-the-box paperwork, Rajiv reveals how to infuse your perspective — your values, goals, and priorities — into every legal document and life plan component so your plan becomes a living system for your future.
Designing Your Ideal Future includes insights from real-world planning examples and a live Q&A with Rajiv Nagaich that answers viewer questions about retirement planning, legal readiness, and family communication. It’s perfect for anyone approaching retirement, currently retired, or responsible for a loved one’s future care — and for those who want a clear, effective approach to planning that prioritizes personal choice and quality of life.
What About You?
You’ve heard Rajiv say it repeatedly: 70 percent of retirement plans will fail. If you know someone whose retirement turned into a nightmare when they were forced into a nursing home, went broke paying for care, or became a burden to their families – and you want to make sure it doesn’t happen to you – then these materials are your key to retirement success.
Visit your local PBS station’s schedule to find airtimes and learn how to access companion resources — including a free Legal Readiness Quiz and tools to help build your complete LifePlanning system.
Don’t remain among the millions of Americans sleepwalking their way into a retirement they never wanted. Instead, your retirement can be the exciting and fulfilling life you’ve always hoped it would be. Start by watching, reading and sharing Rajiv’s important message.
And remember, Age On, everyone!
The post An Agent or Broker Can Help with Medicare Decision, but Choose Wisely appeared first on Home.
