Americans engage in all varieties of planning for retirement. However, most traditional planning remains strictly financial, focusing almost exclusively on whether seniors have enough saved to stop working. We spent last week’s radio program analyzing this precise issue and discussing why traditional retirement planning so frequently fails seniors.
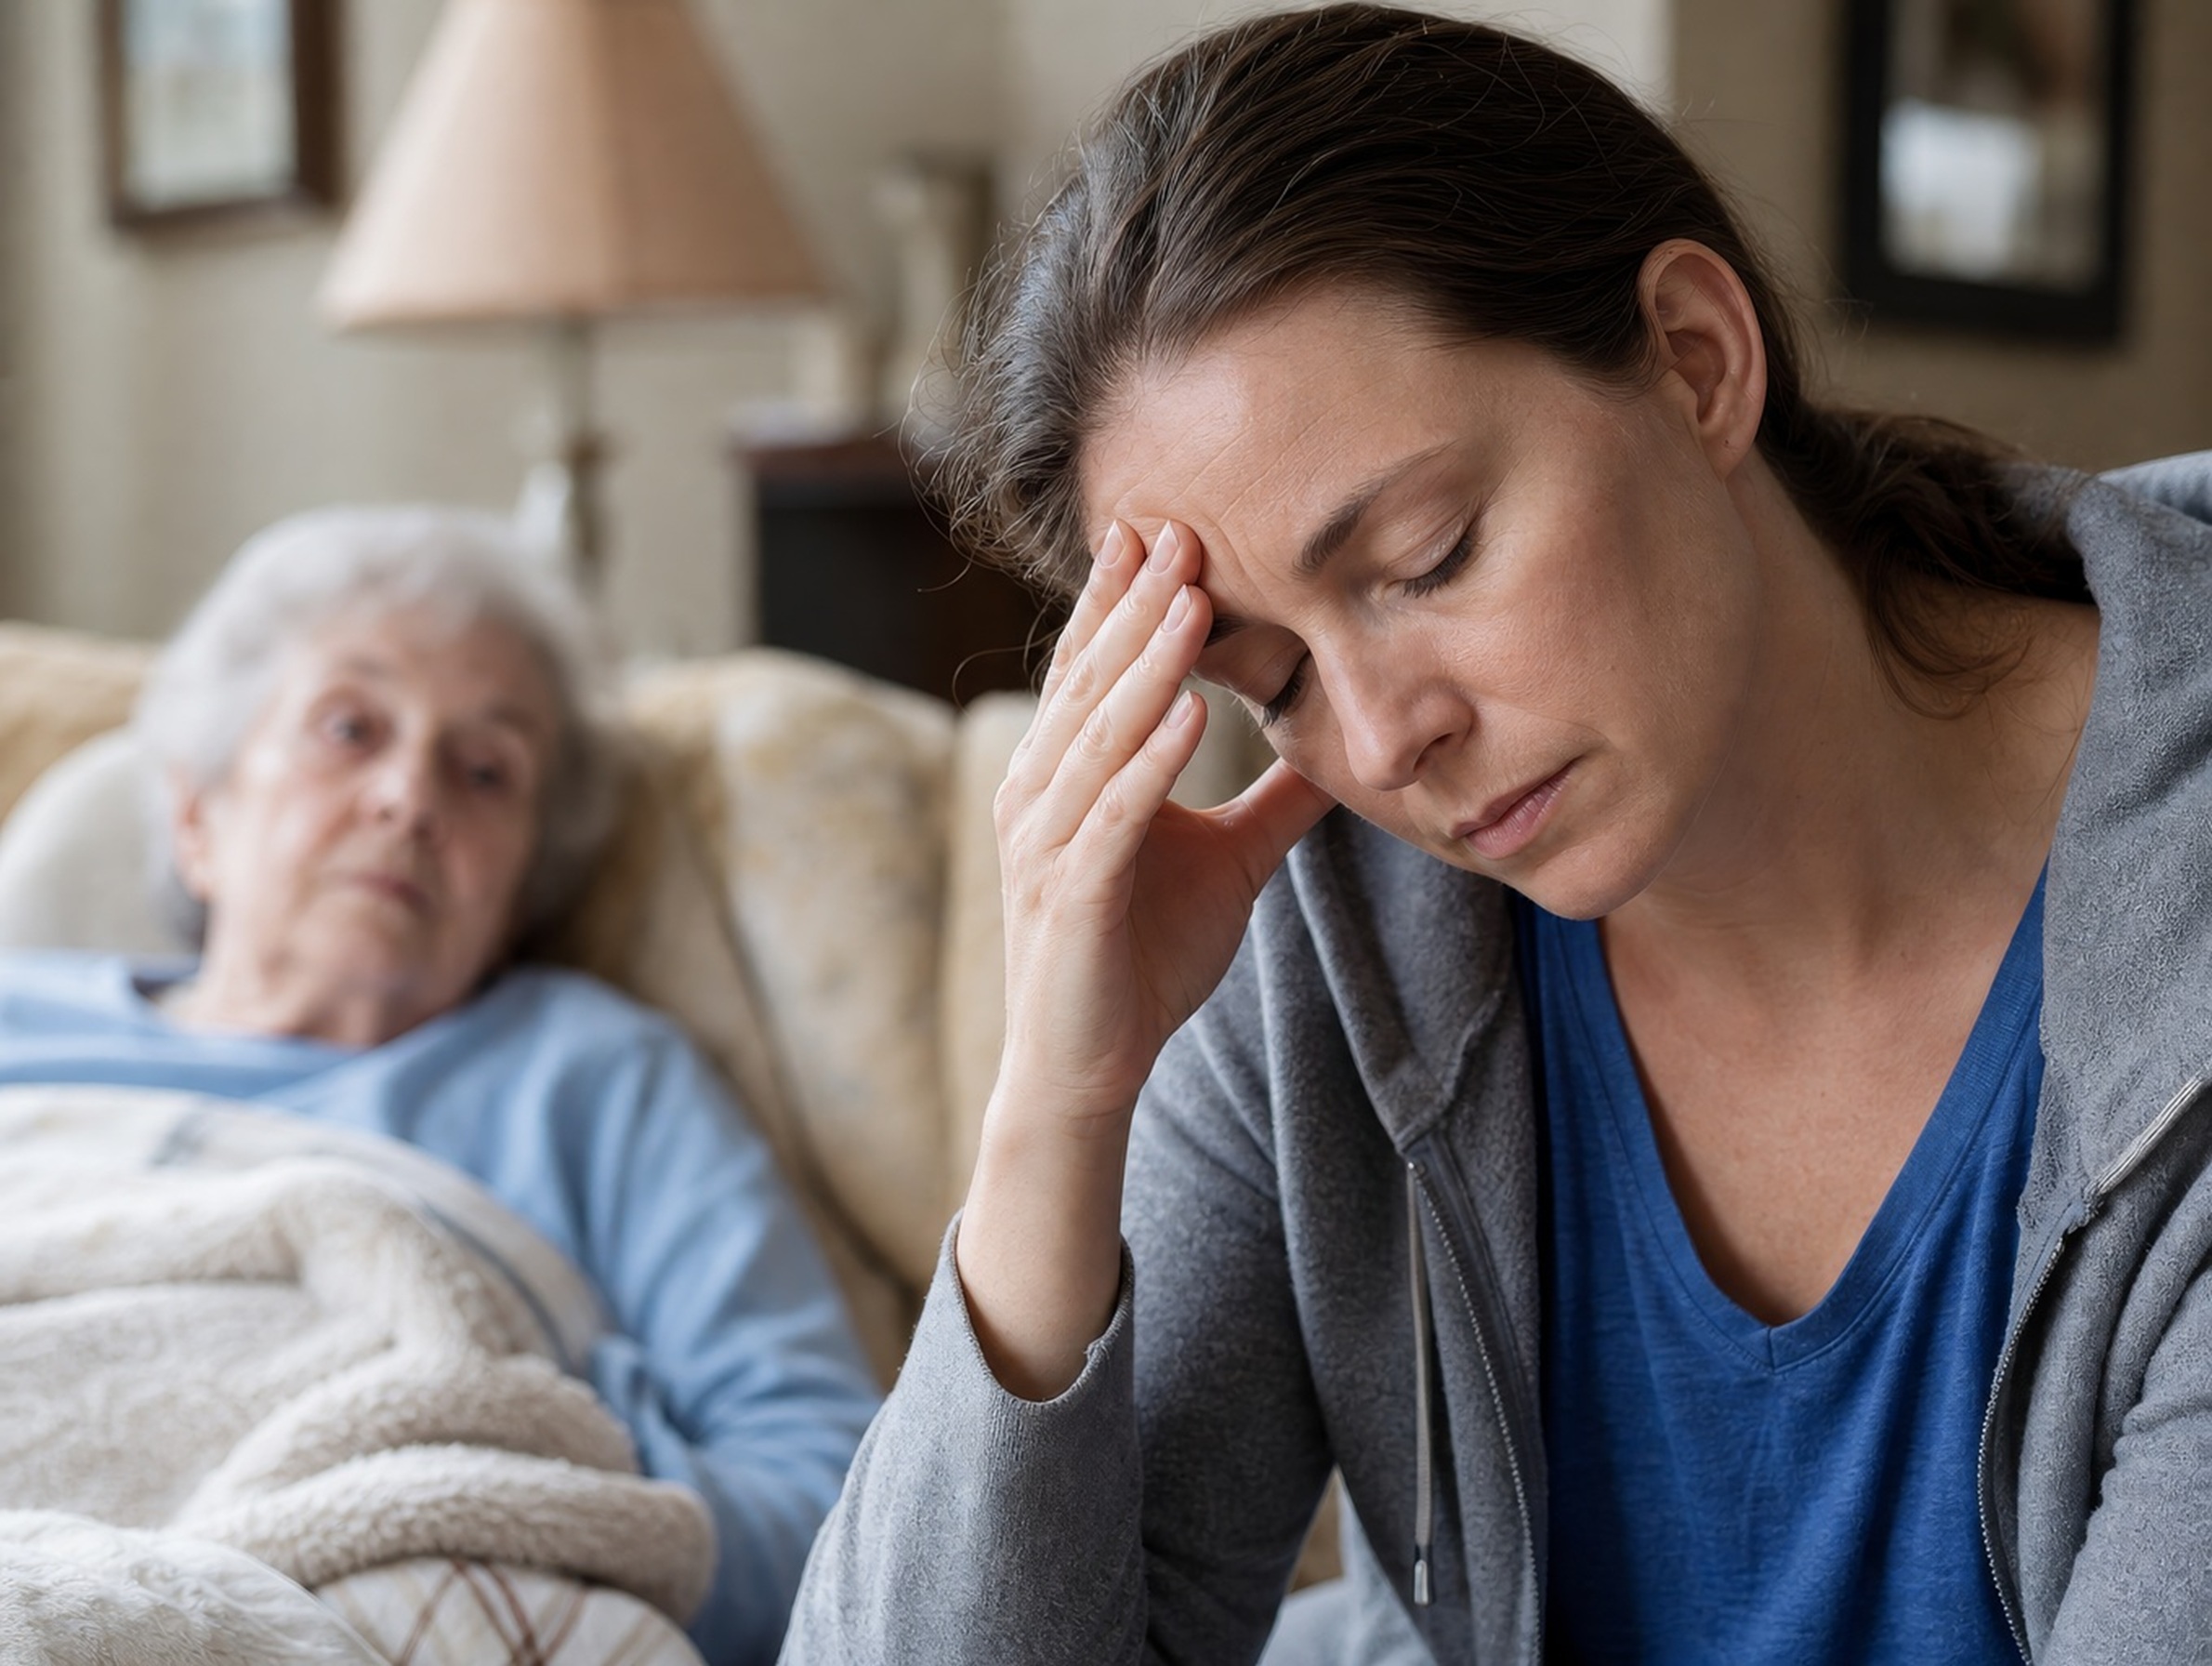
As Rajiv points out frequently, one primary reason for this narrow financial focus stems from a natural reluctance to confront life’s unpleasant realities. A large majority of seniors will eventually face chronic health conditions requiring long-term care. When that day comes, regardless of our best intentions, those closest to us—often our adult children—become deeply involved in the daily physical, emotional, and financial stresses of our care.
A recent article highlights the true magnitude of this challenge. In a piece published by the Washington Post, reporter John Csiszar delivers a simple, urgent message: caregiving is demanding in every possible way. Beyond the emotional toll and physical strain, caregiving causes deep financial damage. The solution, according to Csiszar, lies in comprehensive, proactive planning.
Let’s examine what the Washington Post analysis reveals about these hidden caregiving costs and how families can prepare.
How Casual Caregiving Assistance Can Evolve into Major Commitments
Caregiving is not one-size-fits-all, Csiszar begins; instead, it “comes in a variety of forms, including adult children taking care of aging parents and spouses taking on more daily responsibility for a partner with declining health.”
Often, it can start out as casual support…and evolve into a major commitment.
“For workers, these responsibilities can have seemingly opposite financial ramifications,” Csiszar writes. “While some may need to give up their job earlier than planned to provide care, others may have to stay on the job longer to replace lost wages or savings.”
The Direct Impact of Family Caregiving on Retirement Timelines
In the 2026 Retirement Confidence Survey, conducted by the Employee Benefit Research Institute and Greenwald Research, workers were asked about how caregiving impacted their retirement plans.
“Twenty four percent of workers who provided care said they had moved their target retirement date later,” Csiszar writes. “This compared with 17 percent of workers without such responsibilities. Among retirees, 56 percent noted that they had left work earlier than originally planned, compared with 44 percent of non-caregivers.”
How do we recognize the hidden costs of caregiving and plan for them? Csiszar outlines some ideas for us below.
Understanding Hidden Financial Costs Beyond Direct Care Expenses
When considering the financial burden of caregiving, it’s important to think beyond the resources spent directly on care.
Mary Ware, managing partner and senior wealth adviser at Carnegie Private Wealth, explains, “You also have to think about what you as their caregiver may be giving up — salary, retirement contributions, an employer match, Social Security earnings and, potentially, years of compounding.”
For example, because Social Security retirement benefits are calculated using a worker’s highest 35 years of indexed earnings, these benefits can be reduced if caregivers are forced to leave the workforce before reaching the full 35 years. And even the workers who do reach 35 years can be affected, says Csiszar, since they “may lose the ability to replace lower-earning years with higher ones once they leave the workforce.”
Ware points out that caregiving tends to arise in a person’s life during the peak growth years of their career, in their 40s and 50s. “It’s not the best time to step away,” she says.
Why Advance Long-Term Care Planning Prevents Family Crises
When it comes to the financial options for caregiving, early planning is key.
“The worst time to make a caregiving plan is in the emergency room,” says Jennifer Szakaly, founder and CEO of Caregiving Corner.
She adds that the families that plan before a crisis are able to have better and more thorough discussions about the wishes of the person receiving care, the realistic financial scope of the family, and other details—like where important documents are kept, and who has access to them.
How Proactive Planning Spreads the Burden of Family Caregiving
“Early planning also gives families time to discuss how to spread out caregiving responsibilities and prevent the burden from falling entirely on a single person, who may suffer significant damage to their career and retirement portfolios,” Csiszar writes.
Ware emphasizes the importance of “seeing the whole picture”, especially since families can’t know how long the need for caregiving will last. “Have these conversations as early as possible to gather the true cost,” she says.
There are options for eligible workers, such as the Family and Medical Leave Act, which allows the employees of certain covered workplaces to take up to twelve weeks of job-protected (but unpaid) leave to care for a spouse, child, or parent with serious health conditions. Individual employers may also offer similar paid leave plans, or may be flexible with a worker’s schedule to support their caregiving role when they’re off the clock.
“A family in crisis may have fewer choices than one with a plan in place,” Csiszar writes, concluding his article. “Discussing care preferences, documents, costs and responsibilities in advance can allow the family to chart out a more flexible, workable solution rather than having an emergency dictate the course of action.”
Asking the Critical Question: What Kind of Care Plan Do You Need?
As you might suspect, Rajiv Nagaich has strong opinions on this topic.
“It’s natural,” he says, “that, when there’s a health care crisis, your kids are going to be preoccupied with keeping you safe – never mind that their so-called solution is going to make you miserable. The perspective of your kids and your doctor will be, ‘We have to keep mom or dad safe,’ and that means you’re likely heading for a care facility, which is the one place you always said you never wanted to end up.”
Rajiv adds, “So, the good news is you’ll be 100 percent safe. The bad news: you’ll be 500 percent miserable. There has to be a better way to make sure that, at the end of the day, your perspective is the one that wins out. If you value your independence and the freedom to age at home, it’s up to you to make a plan that makes that outcome the most likely.”
Using a Statement of Care Preferences to Guide Your Family
We’ve written here before about a document some refer to as a Statement of Care Preferences. It’s a tool that lets you lay out in clear detail what type of care you want as you age and what provisions you’ve made to cover the cost.
This document, ideally prepared with your attorney, becomes a blueprint for your family to follow when the need arises.
Follow this link to read the Blog article posted recently about the Statement of Care Preferences.
Partnering with Rajiv Nagaich for Comprehensive Retirement Coaching
Rajiv Nagaich’s newest program on PBS, called Designing Your Ideal Future, is bringing Rajiv’s powerful message to Americans from coast to coast. This engaging and challenging PBS show is prompting thousands to take a fresh look at the type of planning that will help them succeed in retirement.
In this one-hour PBS special, Rajiv Nagaich takes viewers step-by-step through the principles of creating a retirement plan that truly supports the life you want to live. Instead of generic check-the-box paperwork, Rajiv reveals how to infuse your perspective — your values, goals, and priorities — into every legal document and life plan component so your plan becomes a living system for your future.
Designing Your Ideal Future includes insights from real-world planning examples and a live Q&A with Rajiv Nagaich that answers viewer questions about retirement planning, legal readiness, and family communication. It’s perfect for anyone approaching retirement, currently retired, or responsible for a loved one’s future care — and for those who want a clear, effective approach to planning that prioritizes personal choice and quality of life.
Taking Action Today for Long-Term Retirement Security
You’ve heard Rajiv say it repeatedly: 70 percent of retirement plans will fail. If you know someone whose retirement turned into a nightmare when they were forced into a nursing home, went broke paying for care, or became a burden to their families – and you want to make sure it doesn’t happen to you – then these materials are your key to retirement success.
Visit your local PBS station’s schedule to find airtimes and learn how to access companion resources — including a free Legal Readiness Quiz and tools to help build your complete LifePlanning system.
Don’t remain among the millions of Americans sleepwalking their way into a retirement they never wanted. Instead, your retirement can be the exciting and fulfilling life you’ve always hoped it would be. Start by watching, reading and sharing Rajiv’s important message.
And remember, Age On, everyone!
The post Hidden Financial Drain of Caregiving Extends Far Beyond Actual Cost of Care appeared first on Home.
